


Who pays for workers compensation in Utah?
Who Pays for Workers’ Compensation in Utah?
Under Utah law, employers are 100% financially responsible for providing workers’ compensation insurance. It is illegal for a Utah employer to deduct workers’ compensation costs from an employee’s paycheck or force an injured worker to pay for their own work-related medical care.
When you suffer a workplace injury or occupational illness, your benefits—including medical bill coverage, wage replacement, and disability compensation—are paid by your employer’s workers’ compensation insurance policy, an authorized self-insured employer program, or a state fund.
Who Pays for the Insurance Policy?
In Utah, statutory law requires nearly all public and private employers to secure workers’ compensation coverage for their employees from their first day of work. The financial burden of purchasing and maintaining this policy rests entirely on the employer.
Payroll Deductions for Workers’ Comp Are Illegal in Utah
Utah Code § 34A-2-108 explicitly makes it a violation of law for an employer to deduct any portion of a workers’ compensation insurance premium from an employee’s wages.
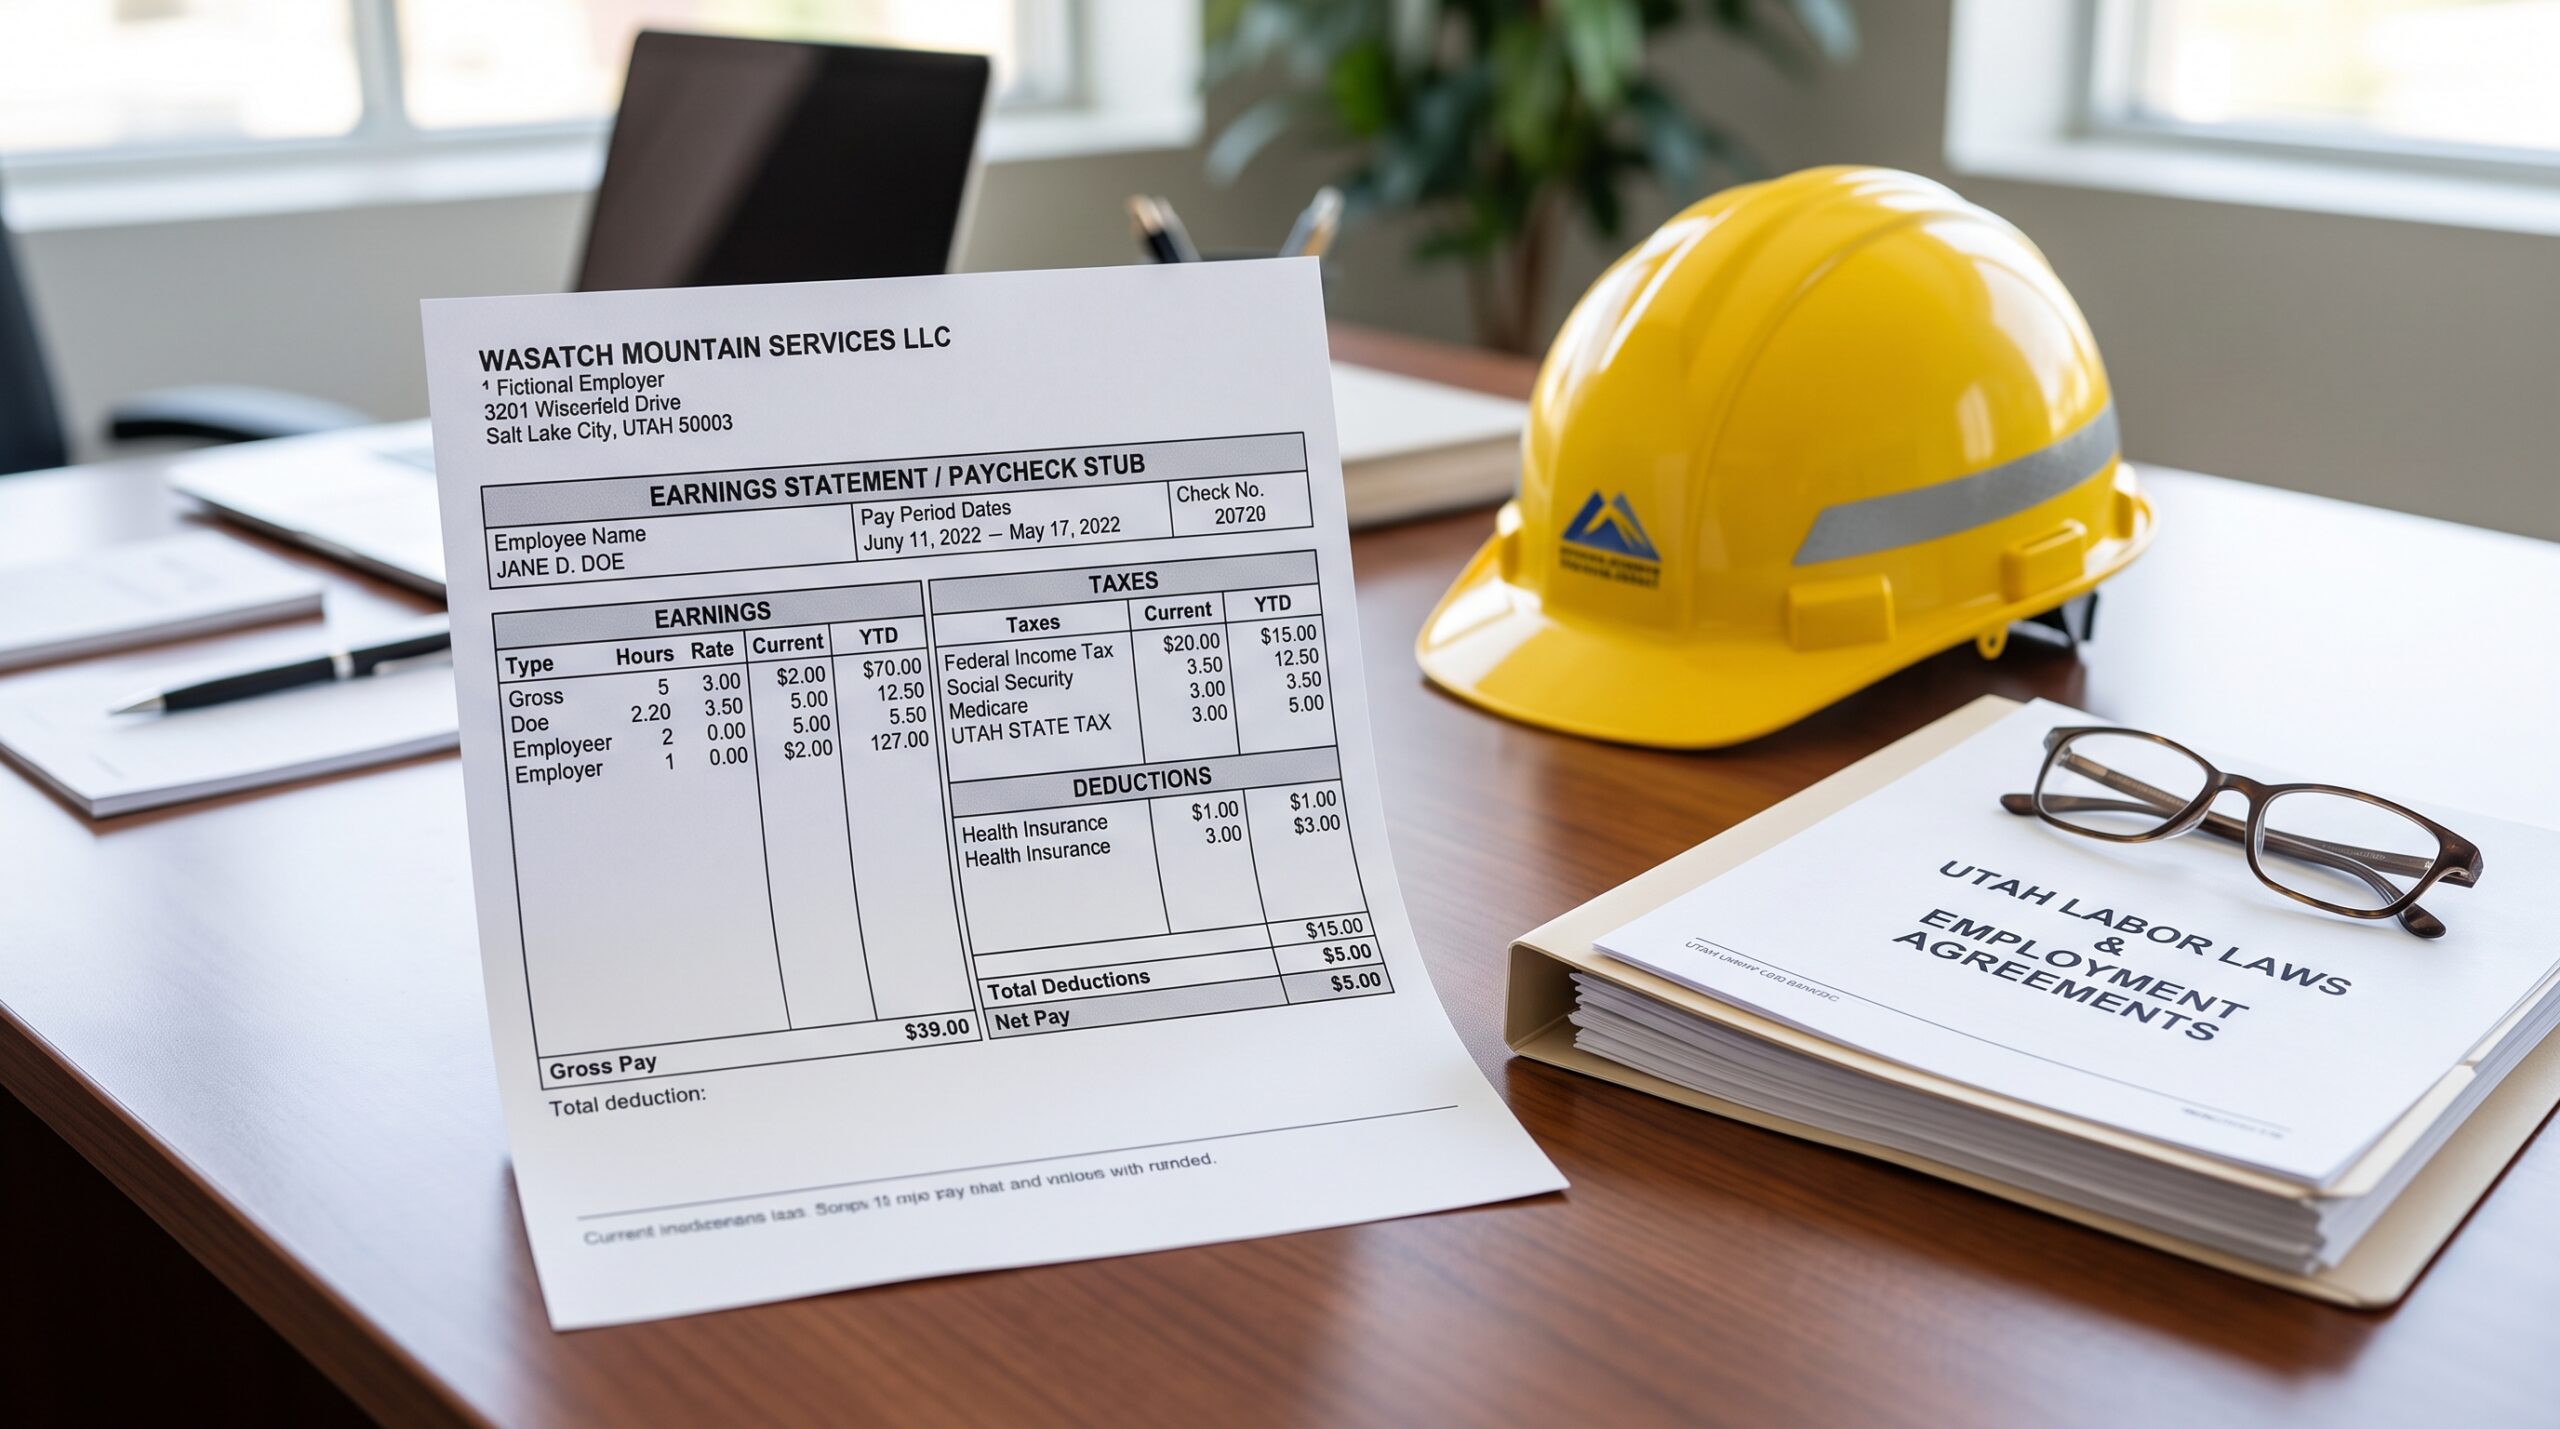
No direct paycheck deductions: Your employer cannot list “workers’ comp” as a payroll deduction on your paystub.
No indirect charging: Your employer cannot reduce your hourly wage or salary specifically to offset insurance costs.
No reimbursement demands: Your employer cannot require you to pay back any part of the insurance premium.
If you notice a line item for workers’ compensation on your Utah paystub, your employer is violating Utah labor laws.
Who Pays Your Medical Bills and Lost Wages After an Injury?
While your employer pays for the insurance policy, they generally do not pay your medical bills or wage loss benefits directly out of their operational business account. Instead, payments are processed through one of three entity structures in Utah:
Commercial Insurance Carriers: Most Utah businesses purchase coverage from commercial insurance carriers licensed by the Utah Insurance Department, like WCF Insurance (formerly Workers’ Compensation Fund). The insurance carrier reviews the claim, authorizes medical treatment, and issues temporary total disability (TTD) checks.
Self-Insured Employers: Certain large companies and government entities in Utah are approved by the Utah Labor Commission to be “self-insured.” These employers pay claims out of their own designated reserves, frequently managed by a Third-Party Administrator (TPA).
The Utah Uninsured Employers Fund (UEF): If an employer illegally operates without workers’ compensation insurance, the Utah Labor Commission administers the Uninsured Employers Fund (Utah Code § 34A-2-704) to provide medical and indemnity benefits to eligible injured workers, while seeking legal reimbursement and penalties directly against the non-compliant employer.
Medical Provider Balance Billing Restrictions
When you receive authorized medical care for a covered workplace injury in Utah, health care providers are prohibited from “balance billing” you.
Under Utah Administrative Code R612-200 and Utah workers’ compensation rules, medical providers must bill the workers’ compensation insurance carrier directly according to the Utah Labor Commission Medical Fee Schedule.
No co-pays: You should not be asked for co-pays or deductibles at doctor appointments for an accepted work injury.
No collection actions: Doctors and hospitals cannot send you to collections for unpaid balances while a workers’ compensation claim is properly pending or accepted.
If you receive a bill from a medical provider you should forward it to the workers compensation adjuster. If you receive collection call or letters regarding a medical bill for treatment of your work injury, you should contact an attorney who specializes in debt defense as such collection action may violate not only state, but federal laws.
What to Do If Your Employer Refuses to Pay or Has No Insurance
Despite clear statutory mandates, some employers attempt to evade their financial obligations. Common warning signs include:
Pressuring you to use personal health insurance: Employers sometimes ask injured workers to file injuries under group health insurance to avoid an increase in their workers’ comp insurance premiums. This is improper and can lead to coverage denials from your health insurer.
Offering to pay “out-of-pocket”: An employer may offer to pay for your immediate clinic visit in cash to keep the accident off the record. If your injury worsens or requires surgery later, the employer often refuses further payment, leaving you without legal protection.
Misclassifying you as an independent contractor: Employers occasionally label workers as 1099 independent contractors to avoid paying workers’ comp premiums. The Utah Labor Commission evaluates actual control over work—not just job titles—to determine whether an employment relationship exists.
If your employer does not have insurance, refuses to report your claim to their carrier, or illegally deducts premiums from your paycheck, you have the legal right to file an Application for Hearing with the Utah Labor Commission’s Division of Adjudication.
When to Consult a Utah Workers’ Compensation Attorney
While the rule on who pays for workers’ compensation is clear, ensuring that the insurance carrier actually pays all the benefits you are owed can be challenging. You should consider speaking with an experienced Utah workers’ compensation lawyer if:
Your employer claims they do not have workers’ compensation insurance.
Your paycheck reflects deductions for workers’ comp premiums.
The insurance company denies your claim or refuses to pay doctor bills.
You are being billed directly by hospitals or medical clinics for a workplace injury.
Your employer is pressuring you not to file a claim.
An attorney can help verify coverage through the Utah Labor Commission database, file claims against the Uninsured Employers Fund if necessary, and ensure your rights are protected throughout the administrative process.
FAQ / FOLLOW-UP QUESTIONS
Can my boss deduct money from my wages for workers’ compensation in Utah?
No. Under Utah Code § 34A-2-108, it is illegal for an employer to deduct any part of their workers’ compensation insurance premium from an employee’s wages.
What should I do if my doctor bills me directly for a work injury in Utah?
Provide the medical facility with your workers’ compensation claim number, insurance carrier name, and billing address. Under Utah Labor Commission rules, authorized medical providers cannot balance bill or send injured workers to collections for covered work injuries.
What happens if my employer doesn’t have workers’ comp insurance in Utah?
If your employer illegally operates without insurance, you can still seek coverage through the Utah Uninsured Employers Fund (UEF), which provides medical and wage benefits to eligible injured workers.
Can an employer force me to use my personal health insurance for a job injury?
No. Personal health insurance plans often exclude work-related injuries, and forcing you to file under personal insurance prevents you from receiving statutory wage replacement and disability protections provided by Utah workers’ compensation law.
Related Articles
- Who pays your health insurance while on workers compensation in Utah?
- Reporting Your Workplace Injury to Your Employer in Utah
- What Does Workers’ Compensation Cover in Utah?
- Utah Workers’ Compensation Guide to Benefits
- Utah Workers’ Comp Denied? 6 Reasons & How to Appeal
Injured on the job? Learn how our team handles Utah work injury claims, or request a free consultation.
Mark Sanchez
Zero out-of-pocket costs, compassionate advocacy, and down-to-earth legal honesty. Our team is dedicated to protecting the rights of hard-working individuals across Utah. Our team provides clear, straightforward guidance throughout every step of your claim—fully backed by bilingual support so language is never a barrier to achieving justice.
*The information provided on this website does not, and is not intended to, constitute legal advice; instead, all information, content, and materials available on this site are for general informational purposes only.